Multifamily property insurance costs rose sharply between 2021 and 2024, and owners have looked at all possible reasons to understand why. Package security regularly comes up for obvious reasons: fewer stolen parcels and fewer claims should result in lower premiums. A multifamily package delivery solution, the access-controlled room where every parcel is logged on arrival, does change your loss picture. Whether it changes your rate, however, is the real question behind reducing insurance premiums through secure mailroom technology.
The honest answer is probably not as a named discount, since no carrier filing or industry document reviewed for this article lists package technology as a rated credit. Still, it can change the risk your underwriter sees at renewal. Owners working to reduce operating expenses at multifamily buildings usually reach insurance last, and this article covers how underwriters price that risk, where package handling falls in, and what to bring to your renewal. It’s general information, so confirm specifics with your own carrier or broker.
Can Secure Mailroom Technology Reduce Insurance Premiums? The Short Answer
There’s no documented, filed insurance credit for package security technology on a multifamily property or general liability policy. Research for this article didn’t find any tangible examples across carriers, brokers, industry bodies, and trade publications. If you see a specific discount percentage attached to package security, you’ll want to attempt to trace it to its source before you believe it. The figures in circulation don’t lead back to a carrier or rate filing.
The intuition behind reducing insurance premiums through secure mailroom technology is still reasonable, because loss control does affect pricing. Homeowners policies carry documented discounts for burglar alarms and deadbolts, while the Insurance Information Institute cautions that not every system qualifies. Commercial multifamily pricing doesn’t work through a menu of line items in the same way.
The real mechanism is straightforward. Underwriters price loss history, claims frequency, and the quality of the risk information you present. A package process can touch all three indirectly, and the sections below show exactly where.
Programs and credits vary by carrier, state, and account. Nothing here about reducing insurance premiums through secure mailroom technology is specific to your policy, so consider every point as a helpful question to ask your broker before coming to any conclusions.
How Multifamily Insurance Premiums Are Priced Right Now
The cost trajectory explains why owners keep asking. The National Apartment Association reported in Premium Pulse: National Multifamily Insurance Cost Acceleration that same-store multifamily property insurance rose from $502 per unit in 2021 to $777 per unit in 2024. That’s a 55 percent increase. Some markets even ran well above it. A Federal Reserve FEDS Note found that insurance reached 5 percent of multifamily revenue in 2024.
Owners are also dealing with the fact that the market has reversed. The Marsh Global Insurance Market Index reports that US property rates declined 13 percent in the second quarter of 2026, the eighth consecutive quarterly decrease.
That leads to an uncomfortable conclusion. Right now, the market cycle moves premiums far more than any building-level control does. Devices installed this year won’t register against a double-digit market swing, and national averages can hide wide local differences.
Loss control still matters, through differentiation. Marsh notes that loss-affected accounts and those with thin risk management data saw more differentiated outcomes. In a falling market, accounts with poor histories or thin information don’t share fully in the decrease. That’s the honest version of reducing insurance premiums through secure mailroom technology: a better position when the market moves, with no discount attached.
Where Package Theft Lands
Start with the coverage boundary. A resident’s stolen parcel is that resident’s personal property, so it generally falls under their own renter’s coverage. It likely doesn’t fall under the building’s property policy, however you’ll want to confirm with the policy to understand the circumstances.
Follow that through, and the premise needs adjusting. The owner’s property policy rarely sees a package theft claim at all. That’s exactly why reducing insurance premiums through secure mailroom technology has no carrier credit behind it, since there’s no loss on the owner’s policy for a credit to offset.
The owner’s exposure is real, but it runs through the operating statement. It shows up as goodwill replacements, staff time spent on disputes, residents who choose not to renew, and negative reviews that mention missing parcels. None of those reach a claim, yet all of them cost money.
The scale is large. The USPS Office of Inspector General recorded at least 58 million packages stolen in the United States in 2024, noting that fragmented reporting complicates the full count. Security.org found that apartment and condo residents were victimized 3.5 times more often than single-family homeowners, with thieves taking $8.2 billion worth of online orders over the past year.
So the usual case for reducing insurance premiums through secure mailroom technology starts in the wrong place. Package theft is an operating cost first.
The Exposure That Does Reach Your Policy
General liability, not property coverage, is where this risk lives.
Consider how deliveries reach many buildings. Couriers arrive and are buzzed in, waved through a side door, or handed a shared code. Once inside, they move unescorted through lobbies and corridors, under unclear authority, often without being asked to sign in. Multiply that by every carrier, gig driver, and grocery delivery service in a day, and the building has a steady flow of non-residents that it can’t account for.
This increases exposure to the premises, which matters because the market prices liability differently from property. Risk and Insurance reported that US property rates dropped 10 percent in the first quarter of 2026, while US umbrella and excess liability risk-adjusted rates rose 18 percent.
That exposure narrows with a credentialed delivery point. Couriers and staff are directed to deliver into an access-controlled room, and each package delivered produces a log. The question for your broker is whether your carrier weighs that, and how your own program treats courier access. This section describes exposure and doesn’t assess liability for any property. Also, it doesn’t constitute legal advice.
If a defensible version of reducing insurance premiums through secure mailroom technology exists, it lives on this side of the policy, as a controlled exposure.
What Underwriters Reward: Fewer Claims and Better Information
Two levers sit within an operator’s control. Neither is a discount, and both affect how your account is priced at renewal.
Claims Frequency, Not Just Severity
Underwriters look for patterns when reading a loss run. One large claim can look like bad luck. A steady run of small claims suggests an ongoing condition of the property and implies the next claim is coming sooner rather than later. Renewals have to price in these expectations.
That’s why properties are often advised to weigh small claims carefully against the deductible. A claim near the deductible returns little, yet it still adds a line to the loss history that the next underwriter will read. Your broker can tell you how your carrier weighs frequency and where your deductible should sit.
This marks the indirect convergence of reducing insurance premiums through secure mailroom technology. The losses it prevents mostly sit on residents’ renter’s policies, as covered above. On the owner’s side, it can reduce incidents that follow uncontrolled access and cluttered common areas: a resident who trips over parcels stacked in a corridor, or a frustrated resident confronting staff in a lobby about a missing package. Those are general liability events, and each one joins the record that an underwriter prices at renewal.
The Quality of Your Renewal Submission
Underwriters only price the risk they can see. A submission that provides evidence for its controls and its loss experience presents a clearer risk than one that describes them in general terms. Documentation is the part of the submission that an operator controls completely.
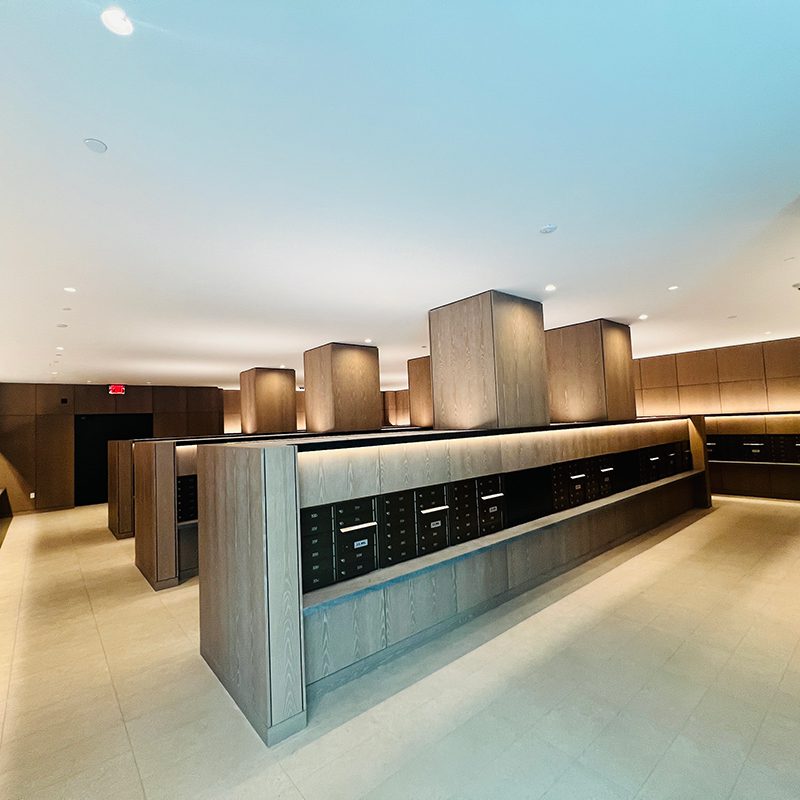
A documented package process produces records that an underwriter can read. With Smart Package Room®, time-stamped delivery logs establish a verifiable chain of custody by documenting every package’s location from the time it is delivered into the room until a resident picks it up. Presence sensors monitor personnel in the room 24/7, and credentialed entry produces a log of who was in the room and when.
Marsh’s second-quarter 2026 index notes that accounts with thinner risk management data saw more differentiated outcomes. Records like these represent vital risk management data.
Be clear about the limit. Better documentation supports a better submission, but it doesn’t guarantee a rate outcome. Only your broker can tell you what your carrier looks for. Tangible evidence is the most defensible form of reducing insurance premiums through secure mailroom technology.
Where the Real Savings Are
If the goal is to reduce the per-parcel cost the property, the operating line is where the money is spent.
The components of package delivery are familiar. Staff hours go to receiving, shelving, searching, and handing over parcels. Missing package disputes take up more time once a parcel can’t be found. Goodwill replacements follow when the property is obligated to cover a loss to protect the relationship with their resident. And in rare cases some residents leave, in part, because deliveries caused them frustration.
There are three reasons why this argument holds up better in a budget conversation. It’s measurable in the property’s own records, from payroll to the replacement log. It doesn’t depend on a carrier’s decision. And it survives being questioned, because every input can be checked by whoever approves the budgetary spend.
A premium argument rests on a credit that’s not published by any carrier, and a market that moves for its own reasons. An owner who approves a package process for its insurance effect will likely be disappointed at renewal. One who approves it for its operating effect can measure the results in the first quarter after instillation. That’s where reducing insurance premiums through secure mailroom technology should hand the argument over to the operating case.
Size the operating side for your own building with the package management cost calculator.
What to Ask Your Broker Before Renewal
To best prepare yourself, bring five questions into the renewal meeting, and tune in to the specifics of the responses. Each one of these questions tests a different part of the case for reducing insurance premiums through secure mailroom technology, so ask all five.
- Which loss-control measures does our carrier recognize? A good answer names the programs and documentation standards. A reassuring response highlights that security always helps.
- What documentation would strengthen our submission? Listen for named records, such as access logs, incident logs, and loss runs.
- How is our claims frequency being weighted? A useful answer refers to your loss run and how many years the carrier reviews.
- What should our deductible strategy be? Expect a recommendation tied to your claims pattern and the current market.
- Are there credits for access control or security programs? A concrete answer is yes or no for your carrier, with the program named. A vague maybe is very likely a no.
Start the conversation well before renewal. Documentation assembled the week before won’t change anything, because the underwriter is reading through the long history.
That’s the straightforward position on reducing insurance premiums through secure mailroom technology. Secure package handling is worth it for reasons that benefit staff and residents, and the insurance line isn’t the strongest.
Frequently Asked Questions About Reducing Insurance Premiums Through Secure Mailroom Technology
1. Does Reducing Insurance Premiums Through Secure Mailroom Technology Work?
Reducing insurance premiums through secure mailroom technology isn’t backed by a named credit that any carrier currently files on a multifamily property policy. No filing or industry document reviewed for this article lists package technology as a rated loss-control measure. The real mechanism runs through claims history and the quality of the risk information you present at renewal, and a documented process can support both. Confirm how your own program works with your broker.
2. Does a Landlord’s Insurance Cover Stolen Packages?
A resident’s parcel is their personal property, so it typically falls under their renter’s coverage as opposed to the building’s policy. Specifics depend on the policy and the circumstances, including whether the property has a record of accepting custody of the parcel. Regardless, owners should understand the boundary because it shapes how a dispute unfolds. A resident who can claim on their own policy behaves differently from one who can’t. This is general information, not advice, so confirm specifics with your carrier.
3. Do Security Cameras Lower Commercial Insurance Premiums?
Documented discounts for alarms and deadbolts exist on homeowners policies, and the Insurance Information Institute notes that not every system qualifies. The commercial multifamily picture is far less clear, with no filed credit that research for this article could verify. This is why claims about reducing insurance premiums through secure mailroom technology deserve the same scrutiny. Ask your carrier directly what it recognizes. Treat any published percentage with caution until you’ve traced it to a carrier.
4. Why Have Multifamily Insurance Premiums Increased so Much?
The National Apartment Association reports that same-store multifamily property insurance costs rose from $502 per unit in 2021 to $777 in 2024, a 55 percent increase. A Federal Reserve analysis found that insurance reached 4.78 percent of multifamily revenue in 2024. The market has since turned, and Marsh reports that US property rates fell 13 percent in the second quarter of 2026. For a renewal budget, market direction matters more than most building-level changes, though accounts with poor loss histories may not share fully in the decrease.
5. What Loss-Control Measures Do Carriers Credit?
Credited measures vary by carrier and program, which makes this exactly the question to put to a broker. The Insurance Information Institute’s homeowner’s guidance points to measures such as sprinkler systems, monitored alarms, and deadbolts. Package security doesn’t appear among the documented measures on multifamily policies. For reducing insurance premiums through secure mailroom technology, the mechanism that applies is indirect: claims frequency and the quality of the risk information presented at renewal.
6. Should You File a Claim for Stolen Packages?
Claims below or near the deductible rarely produce a net benefit, and a pattern of small claims can affect a renewal. Ultimately, this is a decision to make directly with your broker. There’s also a practical point. Most package losses are the resident’s claim to make, under their own renter’s coverage, not the property’s. The owner’s cost usually arrives as goodwill replacements and staff time, two factors that will never reach a claim at all.
7. How Does Documentation Help at Renewal?
Underwriters price the risk they can see, so a property that can produce evidence of its controls and loss experience presents a clearer risk. A documented package delivery and pickup process produces time-stamped delivery logs, room access records, and a dispute history with outcomes. Marsh’s second-quarter 2026 index notes that accounts with thinner risk management data saw more differentiated outcomes. Even though documentation is the defensible core of reducing insurance premiums through secure mailroom technology, it still doesn’t guarantee a rate outcome.
8. Does Courier Access Create Liability Exposure?
Unescorted entry by couriers under unclear authority, with no record of who was in the building, is a general liability question, not a property one. The timing matters. Risk and Insurance reported that US umbrella and excess liability rates rose 18 percent in the first quarter of 2026, even as property rates fell 10 percent. A credentialed delivery point narrows the exposure by logging each entry. How your program treats courier access is a question for your broker, and this isn’t legal advice.
9. Is Package Security Worth the Investment If Insurance Will Not Discount It?
Judge it on the operating case. Failed parcel solutions cost properties in staff hours, dispute handling, goodwill replacements, and resident churn. An argument that doesn’t depend on a carrier’s decision is easier to defend in a budget, because whoever approves it can check every input. Treat any insurance effect as a secondary point to raise with your broker, not as the basis for the decision.
10. What Should You Ask Your Broker About Package Security?
Use three questions verbatim. Which loss-control measures does our carrier recognize? What documentation would strengthen our submission? How is our claims frequency being weighted? A substantive answer names programs, records, and years of loss history, and a reassuring one says security always helps. Raise reducing insurance premiums through secure mailroom technology well before renewal, since documentation assembled late in the cycle changes nothing about the history an underwriter reads.
The Bottom Line
No carrier currently publishes a credit for package security on a multifamily policy, so reducing insurance premiums through secure mailroom technology isn’t a line-item discount. What a documented process can change is the risk your underwriter sees, through fewer liability incidents, better records, and a stronger submission. Confirm policy-specific details with your own carrier or broker.
The fundamentals to remember:
- No line-item discount, because no carrier currently publishes a credit for package security on a multifamily policy.
- Market cycle dominates, given that property rates have fallen for eight consecutive quarters, a swing no single building control can match.
- Liability is the live exposure, since casualty rates are climbing and uncontrolled courier access sits on that side of the policy.
- Documentation differentiates, as underwriters price the risk they can see and reward a submission that shows its controls.
- The operating case is stronger, because staff hours and dispute costs are measurable in your own records.
Reach out to the Smart Package Room team and start with what your process captures today. Walk us through your delivery log, your access records, and your dispute history, and we’ll show you what a documented process records and how it would read in a renewal submission. It’s the practical side of reducing insurance premiums through secure mailroom technology, with no promises attached. Contact our team to set up the walkthrough.